The fastest way to cut monthly expenses is to attack them in three groups, not one long list: recurring bills first (biggest impact, one-time effort), then food and daily spending (medium impact, needs a system), then lifestyle habits (smallest dollar amount per item, but they add up fastest when left unchecked). Most guides give you ten disconnected tips. This one tells you where to start and why.
I started doing this seriously about two years ago, after pulling up three months of bank statements on a Sunday night and realizing I genuinely could not explain about $180 of my own spending. Not one big purchase — just a slow leak of small ones. That audit is still the thing I recommend first, before any specific tip on this list.
Start With a 15-Minute Expense Audit
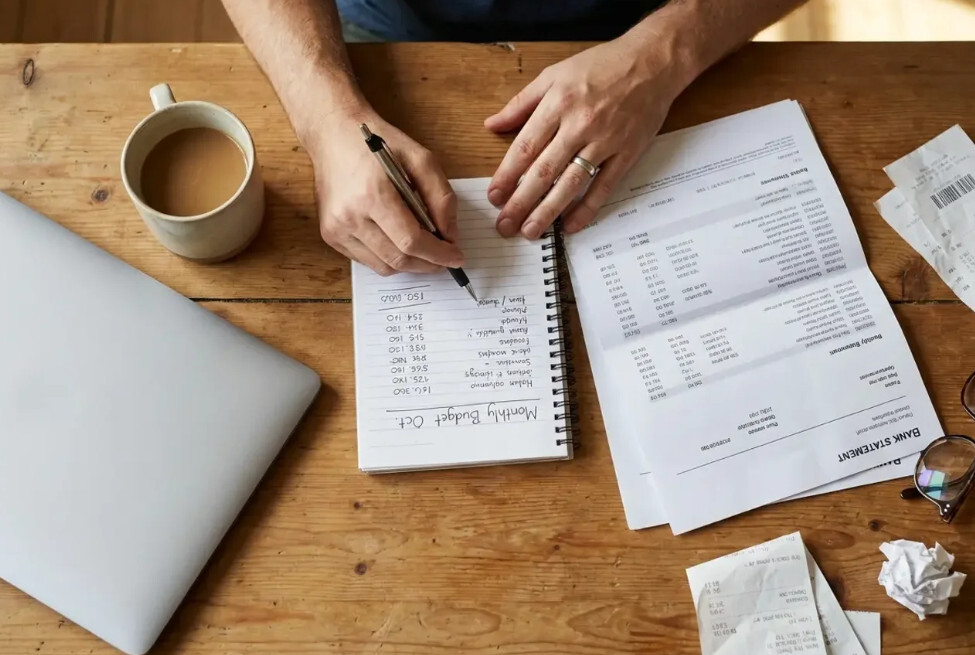
Before cutting anything, you need to know what you’re actually paying for. Pull your last two to three months of bank and credit card statements and sort every line item into one of three buckets: fixed bills, variable daily spending, and “I don’t know what this is.”
That third bucket is the important one. [PERSONALIZE: swap in your own number here — mine was around $180/month across two forgotten subscriptions and a gym membership I hadn’t used in four months]. Most people find at least one recurring charge they forgot existed. That single discovery usually pays for the fifteen minutes it takes to do this.
Once you can see the full picture, the ten cuts below will make a lot more sense — because you’ll know which ones actually apply to your spending, not just to a generic checklist.
Recurring Bills: Cut Once, Save Every Month
These four take the most effort up front but require zero ongoing willpower once they’re done. That’s what makes them worth doing first.
1. Audit every subscription you’re paying for. Streaming services, apps, meal kits, storage plans — list every recurring charge under $50 and ask whether you actively used it in the last 30 days. For a full walkthrough of this process, see our complete subscription audit guide.
2. Call your internet, phone, and insurance providers and ask for a better rate. This one feels awkward the first time. It gets easier. Providers routinely have retention discounts they don’t advertise, and simply asking “is there a lower plan available” or “what can you do to keep me as a customer” works more often than people expect.
3. Raise your insurance deductible if you have a solid emergency fund. A higher deductible lowers your monthly premium, but only makes sense once you have savings to cover it if you need to file a claim. If you haven’t built that cushion yet, start with our guide on how much you should have in an emergency fund before making this change.
4. Refinance or consolidate high-interest debt. If you’re carrying credit card debt or an old loan at a high rate, the interest itself is a monthly expense — often a larger one than people realize. A balance transfer or consolidation loan at a lower rate can free up real cash every month without changing your spending habits at all.
Food & Daily Spending: Needs a System, Not Willpower
This is the category where “just spend less” advice usually fails. It works better with a repeatable system than with discipline.
5. Plan meals around what’s already in your kitchen before you shop. Most food waste — and food overspending — comes from buying without a plan and then ordering delivery because nothing sounds appealing. Even a rough plan for five dinners a week cuts both problems at once.
6. Switch to store-brand for staples you don’t have strong opinions about. Flour, spices, canned goods, cleaning supplies — the quality gap is usually small, and the price gap usually isn’t. Keep brand loyalty for the handful of items where it genuinely matters to you.
7. Set a soft cap on delivery and takeout, and track it separately. You don’t have to cut it out entirely. Just seeing the real monthly total — most people underestimate it by half — tends to change behavior on its own.
Lifestyle Spending: Small Amounts, Fast Leaks
These are the tips people skip because each one sounds too small to matter. Together, they’re often the difference between a budget that works and one that quietly doesn’t.
8. Cancel or freeze memberships tied to habits you’ve already dropped. Gyms, clubs, boxes you subscribed to and stopped opening — these are the easiest cuts on this entire list because you’re not giving anything up. You already stopped using them.
9. Build in one no-spend period a month instead of restricting every day. A single no-spend week is easier to sustain than “cut back a little every day” and tends to reset spending habits more effectively. Our guide on running a no-spend challenge that actually works walks through how to structure one.
10. Route whatever you cut straight into a sinking fund, not just your checking account. Money you save without a destination tends to get spent somewhere else within a month or two. If you’re cutting expenses to prepare for a specific irregular cost — car repairs, holidays, an annual insurance premium — a sinking fund gives that savings a job.
Where to Cut Monthly Expenses for Maximum Savings
Not all ten of these save the same amount, and they don’t take the same effort. Here’s how I’d rank them based on tracking my own budget over the past two years — treat the numbers as a realistic range, not a guarantee.
| Category | Typical monthly savings | Effort to set up | Ongoing effort |
|---|---|---|---|
| Bill negotiation & insurance | $30–$120 | Medium (one phone call) | None |
| Subscription audit | $15–$60 | Low (15 minutes) | Low (check quarterly) |
| Debt refinancing | $20–$200+ | High (research + application) | None |
| Meal planning & food waste | $50–$150 | Medium (weekly habit) | Medium |
| Lifestyle/membership cuts | $10–$50 | Low | None |
[PERSONALIZE: replace this table with your own real numbers once you’ve tracked a month or two — actual figures from your own spending will do more for this post than my estimates will.]
My honest take: if you only do two things from this list, do the subscription audit and the bill negotiation call. Both take under an hour combined, neither requires ongoing willpower, and in my experience they’re the two most likely to actually stick — because you’re not fighting a habit, you’re just removing a line item.
Frequently Asked Questions
How much can you realistically cut from monthly expenses?
Most people who do a full audit find between $150 and $400 in monthly savings without changing their quality of life significantly — usually a mix of forgotten subscriptions, negotiable bills, and reduced food waste. The exact number depends heavily on how much “fat” is currently in your budget.
What’s the easiest expense to cut first?
Unused subscriptions. They require no negotiation, no habit change, and no lifestyle sacrifice — just canceling something you already weren’t using.
Should I cut expenses or increase income first?
Cutting expenses usually pays off faster, since it takes effect immediately and doesn’t depend on finding new income. That said, they’re not mutually exclusive — many people do a quick expense audit first, then use the freed-up cash flow to fund a side income project without financial pressure.
Is it worth canceling all subscriptions to save money?
Not necessarily. The goal isn’t zero subscriptions — it’s zero subscriptions you’re not using. Canceling something you genuinely value just to hit a savings number usually doesn’t last.
How often should I re-check my monthly expenses?
A full audit every 2–3 months catches new subscriptions or price increases before they pile up. Providers frequently raise rates quietly, so even bills you negotiated once can creep back up.
This post is part of our Budgeting & Saving series. If you’re just getting started, check out how to build a budget from scratch or learn about the 50/30/20 budgeting rule.