I still remember sitting at my kitchen table one Sunday evening, feeling genuinely proud of myself. I had just built what I thought was the most realistic, detailed budget I’d ever made — every category mapped out, a separate column for “fun money,” even a little savings buffer. I texted a friend: “I think I finally figured it out.”
Three weeks later, I was overdrawn.
If that story sounds familiar, you’re not bad at math, and you’re not undisciplined. The real reason your budget fails every month is more subtle — and once you see it, the fix becomes obvious.
Why a “Perfect” Budget on Paper Still Crashes in Real Life
Most budgeting advice stops at the spreadsheet. Make a list, assign percentages, track your spending — done. But that approach treats budgeting as a math problem, when it’s actually a behavior problem.
Research from behavioral economics shows that humans are famously bad at predicting their own future spending. We underestimate irregular expenses (the dentist, the car repair, the birthday gift that snuck up on us) and overestimate our willpower when we’re tired, stressed, or just had a rough Tuesday. A budget built on “how I plan to spend” versus “how I actually spend” is already starting on shaky ground.
There’s also something called planning fallacy — a well-documented cognitive bias where we consistently assume future tasks (including sticking to a budget) will go more smoothly than past ones. So every month, we rebuild the same optimistic plan, and every month, the same unpredictable life shows up uninvited.
The “Invisible Expenses” Problem Most Budgets Ignore
Here’s a test: when you built your last budget, did you include a line for annual subscriptions? What about car registration? Vet visits? A friend’s wedding gift? These aren’t surprises — they’re just irregular. The problem is that most budget templates only model monthly cash flow, which makes anything that doesn’t repeat on a 30-day cycle essentially invisible.
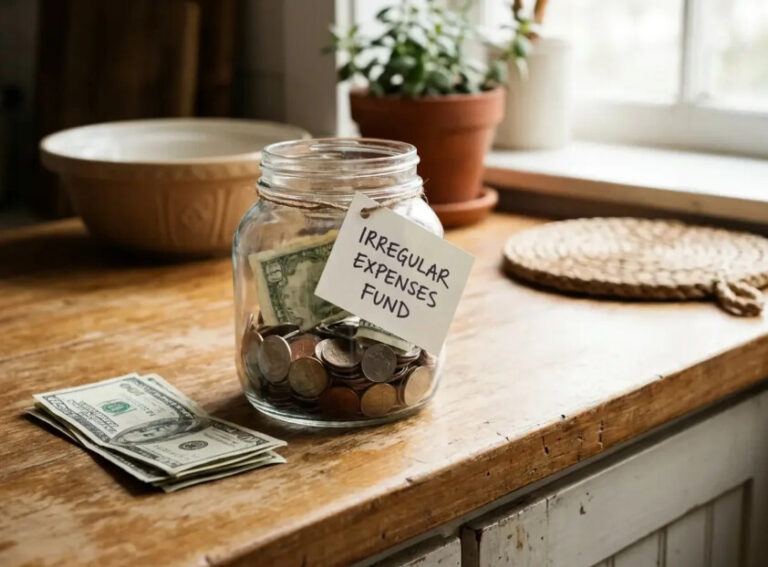
One practical fix: add what some financial planners call a “sinking fund” — a catch-all category where you set aside a small amount every month for expenses that will come eventually but not on a predictable schedule. Even putting aside $50–$100 a month for “life happens” costs can prevent the spiral where one unexpected bill blows up an otherwise solid month.
According to the Consumer Financial Protection Bureau (CFPB), irregular and infrequent expenses are one of the top reasons people fall short of their budgeting goals — yet they’re rarely the first thing a budgeting app asks you to plan for.
The 3 Most Common Ways Budgets Break (That No App Will Tell You)
After talking with dozens of people about their financial habits — and failing at my own budgets more times than I’d like to admit — I’ve noticed the same patterns repeating. These aren’t about self-control. They’re structural problems that any budget can fall into.
1. You’re Budgeting Your “Average” Month, Not Your Real One
Most people build a budget by looking at two or three recent months and averaging them out. That works fine if your life is consistent — but most people’s aren’t. One month you have a birthday party, a car oil change, and a surprise medical copay. The next month, nothing. If your budget assumes the quiet month every time, it will fail during the noisy one.
A better approach: look at 6–12 months of actual spending before you build your budget. This isn’t fun. But it’s the only way to see your real spending patterns — including the irregular ones that always seem to catch you off guard.
2. Your Budget Has No Room for “Human” Decisions
Rigid budgets assume you’ll make perfectly rational decisions every time. You won’t. Nobody does. The friend who invites you to dinner at a restaurant that’s slightly over budget. The sale that’s genuinely a good deal but wasn’t planned. The day you’re exhausted and spend $18 on takeout instead of cooking that chicken you already bought.
These aren’t failures — they’re normal human behavior. A budget that punishes you for being human will make you want to abandon it entirely. Instead, build in a “no-guilt” spending category — sometimes called a “guilt-free” or “personal spending” bucket. Even a modest amount of truly discretionary spending you never have to justify can be the safety valve that keeps you engaged with the process long term.
3. You’re Treating Your Budget as a One-Time Event
A budget is not a document you make in January and then reference in August when something goes wrong. It’s a living system that needs to be updated as your life changes — a raise, a new subscription, a change in commuting costs, a relationship that affects household expenses.
The people I’ve seen succeed with budgeting long-term do some version of a weekly or bi-weekly “money check-in” — not a full audit, just 10–15 minutes of looking at where things stand and making small adjustments before they snowball. The IRS even provides a free withholding estimator to help you plan around tax changes — the kind of annual shift that can quietly throw off a budget you thought was locked in.
What Actually Works: A Flexible Budget Framework That Survives Real Life
I want to be clear: there’s no single budget method that works for everyone. But after years of trying everything from strict envelope systems to full zero-based budgeting, here’s what I’ve found to be the most sustainable approach for most people — especially those who’ve tried before and felt like they failed.
Start With Your Non-Negotiables, Not Your Goals
Most budgeting guides tell you to start with your goals: save X%, invest Y%. But for people who’ve struggled with budgeting, starting with goals often leads to unrealistic plans and early discouragement.
Instead, start with your non-negotiables — the expenses that would genuinely disrupt your life if you skipped them. Rent, utilities, groceries, transportation, minimum debt payments. These are your foundation. Everything else — savings, investing, fun money — gets layered on top once you know exactly what you’re working with.
Use the “Good Enough” Rule, Not the “Perfect” Rule
Perfectionism is one of the most underrated reasons budgets fail. People miss one week of tracking and feel like the whole month is ruined, so they stop tracking entirely. Or they go $40 over in one category and feel like failures, so they “start fresh next month.”
A budget that’s 80% accurate and sticks around for six months will do more for your finances than a 100% accurate budget that you abandon after three weeks. Give yourself explicit permission to be imperfect. Budget for “miscellaneous” deliberately. Stop treating a single overage as proof that you can’t do this.
If you’re just getting started, our guide on How to Start Investing With $100 shows how even small, consistent financial decisions build into meaningful progress over time — the same principle applies to budgeting.
Track Your “Spending Triggers,” Not Just Your Spending
This one changed things for me more than any spreadsheet. Instead of just recording what I spent, I started noting why I spent it — not in a judgment way, just observationally. What was happening right before that unplanned purchase? Was I stressed? Bored? Celebrating something?
Patterns emerge quickly when you do this for even a few weeks. Most people have two or three specific triggers that account for the majority of their unplanned spending. Once you know what yours are, you can plan around them — or at least anticipate them instead of being blindsided.
The Psychology Behind Why You Keep Restarting Every Month
Let’s talk about something that doesn’t get nearly enough attention in personal finance circles: the emotional cycle of budgeting.
It usually goes like this. You feel motivated — a financial stress, a new year, a big purchase on the horizon. You build the budget with genuine enthusiasm. For a week or two, you’re tracking everything. Then something happens. An unexpected expense, a social situation that blows a category, a stressful week where tracking was the last thing on your mind. Suddenly you’re not just off-budget — you feel like you’ve failed. And because you feel like a failure, you stop engaging entirely until the next motivation spike hits.
Behavioral economists call this the “what-the-hell effect” — once we violate a rule we’ve set for ourselves, we tend to abandon it entirely rather than just resuming. It’s the same reason people eat an entire pizza after having one slice they didn’t plan for on a diet.
The fix isn’t more willpower. It’s lowering the stakes of individual failures. Make your budget resilient to imperfection by design — not something that shatters the moment real life shows up.
A Practical Checklist Before You Build Your Next Budget
Before you open that spreadsheet or app again, run through this quickly:
| Question | What to Do If the Answer Is “No” |
|---|---|
| Have I looked at 6+ months of actual spending? | Pull your bank and card statements first — don’t guess |
| Do I have a category for irregular annual expenses? | Add a “sinking fund” line, even if it’s small |
| Is there a guilt-free spending category with no required justification? | Add one — it’s not a failure, it’s a safety valve |
| Have I planned a time to review this at least twice a month? | Schedule 15 minutes on your calendar now, before you forget |
| Does my budget have any flexibility built in for overage? | Add a 5–10% buffer to categories that historically run over |
If you’re also thinking about what to do with money once your budget stabilizes, it’s worth reading about Common Investing Mistakes — because the same behavioral biases that derail a budget often show up in early investing decisions too.
Frequently Asked Questions About Why Budgets Fail
Why does my budget always fail in the third week of the month?
The third week is where irregular and social expenses tend to cluster — midmonth bills, weekend plans, and the gradual erosion of your early-month discipline. If you consistently run short around this time, consider front-loading your savings contributions and fixed expenses in the first week, so whatever remains is genuinely available to spend.
Is zero-based budgeting better than the 50/30/20 method?
Neither is objectively better — they suit different people and circumstances. Zero-based budgeting (where every dollar is assigned a purpose) works well for people who want tight control and are willing to put in the time. The 50/30/20 rule (needs/wants/savings) is easier to maintain and better for people who want structure without obsessive tracking. The best budget is the one you’ll actually stick with.
How many budget categories should I have?
Fewer than you think. Most people do better with 8–12 broad categories than with 30 hyper-specific ones. Over-categorization creates friction, and friction kills consistency. When tracking feels like a part-time job, people stop doing it.
Should I use a budgeting app or a spreadsheet?
Whichever you’ll actually open regularly. Apps that sync with your accounts reduce the friction of manual entry, which helps consistency. But if you prefer the control and clarity of a custom spreadsheet, that works just as well — the tool matters far less than the habit of using it.
What if my income is irregular — can I still budget?
Yes, but the approach shifts. Instead of budgeting by month, budget by paycheck or by income event. Build around a “baseline” income (your realistic low month) and treat anything above that as discretionary. The principle of covering your non-negotiables first applies even more urgently when income fluctuates.