The month I hit my personal budget burnout wall wasn’t dramatic. There was no big purchase, no emergency, no fight about money. I just… stopped opening the app. For three weeks I ignored every transaction alert, skipped my usual Sunday check-in, and told myself I’d “catch up later.” Later never came. By the time I looked again, I’d overshot my dining budget by $200 and had no idea where it went.
If any of that sounds familiar, you’re not alone — and more importantly, you’re not broken. Budget burnout is a real, documented response to financial stress and over-restriction. The goal of this post isn’t to lecture you about getting back on track. It’s to show you a way to reset that actually works, without pretending willpower alone is the answer.
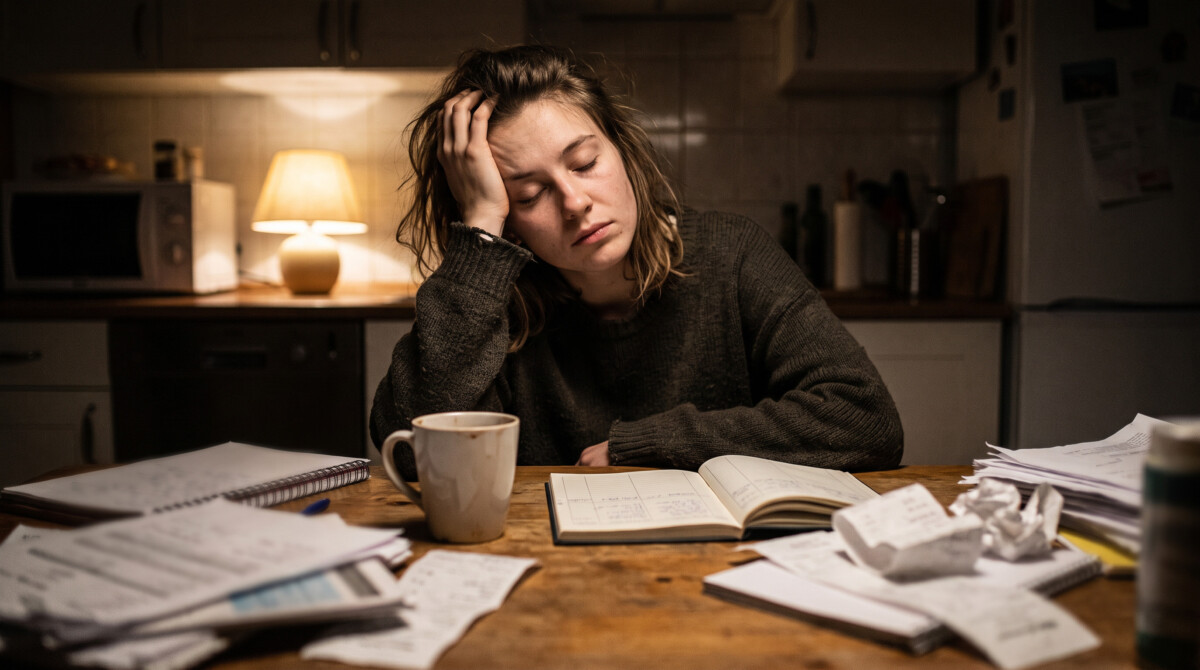
What Is Budget Burnout — and Why Does It Keep Happening?
Budget burnout isn’t laziness. Behavioral economists like those at the Consumer Financial Protection Bureau (CFPB) describe financial fatigue as a genuine form of decision exhaustion — your brain has made so many spending decisions under stress that it starts looking for any exit. The result: you check out entirely.
The most common triggers I’ve seen (and felt) break down like this:
- The budget was too restrictive from the start. If your plan leaves zero margin for error, the first slip feels catastrophic. People quit not because they failed once, but because the plan had no forgiveness built in.
- The tracking itself became the punishment. Logging every $4 coffee felt like self-surveillance. After a while, the app became a source of guilt rather than a useful tool.
- External stress bled into financial anxiety. A rough patch at work, relationship tension, or health worries have a way of making financial tasks feel impossible — even when your actual numbers are fine.
- Progress wasn’t visible enough. Budgeting without a clear goal feels like running on a treadmill. When the destination isn’t in front of you, you stop caring about the pace.
The fix for budget burnout, it turns out, isn’t more discipline. It’s better design — building a system that’s resilient enough to survive the messy weeks.
How to Tell If You’re in Budget Burnout (vs. Just Having a Bad Month)
A bad month is a one-time derailment. Budget burnout is a pattern. Here’s a quick gut-check:
| Bad Month | Budget Burnout |
|---|---|
| You overspent in one category | You stopped checking spending entirely |
| You feel frustrated but motivated to fix it | You feel avoidance, guilt, or apathy toward money |
| You can name what went wrong | You can’t quite explain what happened — you just checked out |
| You expect to course-correct next month | The idea of restarting feels exhausting or pointless |
If you’re reading this in the burnout column, that’s actually useful information — because it tells you the problem isn’t your spending, it’s your system.
The Budget Burnout Reset: A 5-Step Approach That Doesn’t Require Willpower
Step 1: Stop the Audit Spiral First
The instinct when you fall off a budget is to do a detailed forensic review — where did every dollar go, what went wrong, how bad is it? Resist this, at least for the first 48 hours. When you’re already in burnout, a deep audit feels like self-punishment, and the emotional weight of it can push you further into avoidance.
Instead, do a “30-second look.” Open your bank app, scan the balance, close it. That’s it. You just proved to yourself that looking doesn’t hurt. Do this once a day for a few days before you go deeper. I know it sounds too small to matter — but this is how you rebuild the habit of not avoiding.
Step 2: Write a One-Line Diagnosis, Not a Novel
When you do sit down to assess what happened, keep it simple. The goal is one sentence: “I burned out because ___.” Not a five-page breakdown with color-coded categories. Just the honest core of it.
Some real examples from people I’ve talked to: “I burned out because I set a grocery limit that was unrealistically low for our household.” Or: “I burned out because I was tracking every single purchase and it felt like punishment.” Or: “I burned out because I had no buffer, and one unexpected car repair broke the whole system.”
One line. That’s your starting point.
Step 3: Rebuild With One Rule, Not Twenty
Here’s the mistake most people make at the reset stage: they try to rebuild the full system immediately. New app, new categories, new spending limits, new savings rules — all at once. Within two weeks they’re exhausted again.
Instead, pick one anchor rule and stick to it for 30 days. Nothing else. It might be:
- Check your balance every Sunday morning, no action required.
- Keep $200 in a buffer account that you don’t touch.
- Track only your top-two spending categories (usually food and entertainment).
The point isn’t to run a perfect budget. It’s to rebuild the behavior of engaging with your money without dreading it. Complexity comes later, after the habit is solid again. If you’re just getting back into budgeting basics, our guide on how to build a budget from scratch walks through a low-friction starting framework.

Step 4: Build In “Planned Imperfection”
This is the piece most traditional budgeting advice leaves out. A budget that has no flexibility isn’t a sustainable budget — it’s a diet waiting to fail. Behavioral economists call this the “what the hell” effect: once you break a strict rule even slightly, you abandon it completely.
The fix is to plan for imperfection explicitly. Here are two ways to do it:
Option A — The Flex Fund. Set aside a small, defined amount each month (I used $75) labeled “no-questions-asked spending.” It doesn’t need to be tracked, categorized, or justified. When you use it, you’re not breaking a rule — you’re using a rule you already built.
Option B — The Forgiveness Window. Allow yourself one category per month to overspend by up to 15% without guilt. Which category matters less than the principle: you’re giving yourself a release valve. The CFPB’s financial well-being research consistently shows that financial stress, not spending per se, is the primary driver of poor long-term financial decisions — reducing the stress of rigid rules tends to improve outcomes, not worsen them.
Step 5: Change the Scoreboard
One underrated reason budget burnout keeps recurring: people track whether they stayed under budget (a negative metric — “did I fail?”) instead of tracking what they’re building toward (a positive metric — “am I getting closer?”).
This is not a small distinction. After a reset, shift your primary scoreboard to a forward-looking goal:
- Instead of: “Did I stay under $400 in groceries?” → “Am I on track to hit $1,000 in my buffer fund by December?”
- Instead of: “Did I avoid impulse spending?” → “Is my emergency fund balance growing every month?”
- Instead of: “Did I follow all 12 budget categories?” → “Did I do my weekly check-in?”
The shift from restriction-focused to progress-focused budgeting is one of the most reliable ways to make the whole thing feel different. If you need a goal to anchor to, check out our post on building a $1000 emergency fund — it’s one of the clearest short-term targets that gives budgeting a concrete purpose.
What to Do When You Fall Off Again (Because You Will)
Here’s something I wish someone had told me earlier: falling off a budget reset is not a sign that you’re not built for this. It’s a sign that you’re human, and that the system needs one more adjustment. The goal is not a perfect 12-month run. The goal is a shorter and shorter gap between falling off and getting back on.
Track that gap instead. The first time I burned out, it took me three months to look at my finances again. The second time, three weeks. The third time, I caught it in about five days. That’s what progress in personal finance actually looks like — not a perfect record, but a faster recovery.
If you’re finding that burnout keeps cycling back, it’s worth asking whether your budget category structure is the root problem. Automated savings, in particular, can dramatically reduce the mental load of budgeting because the decision happens once. We cover that in detail in our post on how to automate your savings.
The Psychology Behind Why Budgets Fail (And How This Changes Your Approach)
Understanding a few behavioral patterns can make the reset feel less like a character test and more like a design problem. Here are three that matter most for budget burnout specifically:
Present bias. We systematically undervalue future rewards compared to present ones. This is why “save for retirement” feels abstract but “I want this jacket now” feels urgent. Budget systems that only appeal to long-term goals tend to lose to short-term impulses. The fix: attach near-term milestones that you can see and feel, even if they’re small. Three months of a stable buffer fund beats a 30-year projection chart in terms of motivation.
Ego depletion. Decision-making capacity is finite. Every micro-decision you make about spending (should I get the coffee? should I split the tab differently? do I need this?) drains the same pool of mental energy you use for everything else. Budgets with dozens of fine-grained categories require more decisions, not fewer. Simpler structures with wider buckets actually preserve more cognitive energy for the choices that matter.
Loss aversion. We feel losses roughly twice as intensely as equivalent gains. A budget framed entirely around “what you can’t spend” triggers loss aversion constantly. Reframing even subtly — “this month I’m building a $500 buffer” rather than “this month I’m cutting dining by $100” — shifts the psychological direction of the whole exercise.
According to financial well-being research supported by the Federal Reserve’s annual household economic well-being survey, adults who report feeling “in control” of their day-to-day finances are significantly more likely to have built financial buffers and weathered unexpected expenses — suggesting that the psychological framing of financial control matters as much as the dollars themselves.
Quick-Reference: Budget Burnout Reset Checklist
| Step | Action | Time Required |
|---|---|---|
| 1 | Stop the spiral — do a 30-second balance check only | 30 seconds/day for 3 days |
| 2 | Write one-line diagnosis of what caused burnout | 5 minutes |
| 3 | Choose one anchor rule for the next 30 days | 10 minutes |
| 4 | Add a Flex Fund or Forgiveness Window to your budget | 15 minutes |
| 5 | Switch your scoreboard to a forward-looking goal | 10 minutes |
Frequently Asked Questions About Budget Burnout
What causes budget burnout?
Budget burnout typically results from over-restriction, decision fatigue, or a mismatch between a rigid budget plan and unpredictable real-life spending. When a budget leaves no margin for error and requires constant decision-making, the mental cost eventually outweighs the perceived benefit and people disengage entirely.
How long does it take to recover from budget burnout?
Recovery varies by person and by how long the burnout lasted. With a structured reset approach — starting small and rebuilding one habit at a time — most people feel re-engaged within two to four weeks. The goal isn’t instant perfection; it’s a shorter and shorter gap between falling off and getting back on.
Is it normal to quit your budget multiple times?
Yes, and it’s more common than most people admit. Research in behavioral finance consistently shows that budgeting is a habit that most people have to rebuild several times before it sticks. Each restart is a data point about what your previous system got wrong — not evidence that you’re bad with money.
What’s the easiest budget to maintain without burning out?
The easiest sustainable budget is the one with the fewest active decisions. A three-bucket approach (fixed expenses, savings, everything else) with automated savings transfers tends to outperform detailed category-by-category tracking in terms of long-term adherence. Fewer rules, consistently followed, beats a perfect system that gets abandoned.
Should I use a budgeting app after a burnout reset?
Only if you find it genuinely useful rather than anxiety-inducing. For some people, an app creates helpful visibility. For others, it becomes a source of guilt and surveillance. Consider starting post-reset with a manual method — a simple spreadsheet or even a notebook — before reintroducing an app. Let your comfort with the data guide the tool choice, not the other way around.
How is budget burnout different from just not caring about money?
Budget burnout is an active withdrawal driven by anxiety, fatigue, or a sense of futility — you still care about your finances, you’re just avoiding them. Not caring is a more passive state. The distinction matters because the fix for burnout is reducing friction and redesigning the system, while “not caring” typically has a different root cause that’s worth examining separately.